


Short answer: crypto is already in a bear market under the simple “20% below the high” definition, but the broader evidence does not yet show full, market-wide capitulation. As of October 13, 2026, Bitcoin is about 34.1% below its October 2025 record , U.S. spot Bitcoin ETFs have lost roughly $451.7 million in October through October 12, and monetary policy remains restrictive. At the same time, Bitcoin’s MVRV is 1.54 , price remains about 11.7% above the short-term-holder cost basis , and total stablecoin supply is still up over 30 days.
BlockchainReporter therefore classifies the current environment as a bear-market transition / bear-warning regime , not a confirmed capitulation phase. That is an editorial classification, not a statistical trading signal.
Crypto bear-market dashboard: October 13, 2026
The table below uses a UTC market snapshot and separates direct measurements from editorial interpretation.
| Indicator | Current reading | What would strengthen the bear case? | Current status |
|---|---|---|---|
| Bitcoin drawdown from ATH | About −34.1% from $126,277.05 | Failed recoveries and a sustained sequence of lower highs | Warning |
| Time since Bitcoin ATH | 371 days | Continued weakness after a full year without reclaiming the peak | Warning |
| MVRV | 1.54 | A move toward or below 1, showing aggregate holders near or under cost | Mixed; not capitulation |
| Short-term-holder realized price | $74,509.50; BTC about 11.7% above it | Price remains below the level for multiple weekly observations | Not confirmed |
| U.S. spot Bitcoin ETF flows | About −$451.7M from Oct. 1–12 | Persistent multiweek outflows during failed rallies | Warning |
| Stablecoin market cap | $305.933B; −0.54% in 7d, +0.72% in 30d | Sustained 30-day contraction in available crypto liquidity | Mixed |
| Federal funds target range | 3.75%–4.00% | Further tightening or delayed easing with elevated inflation | Macro headwind |
Additional cross-checks:
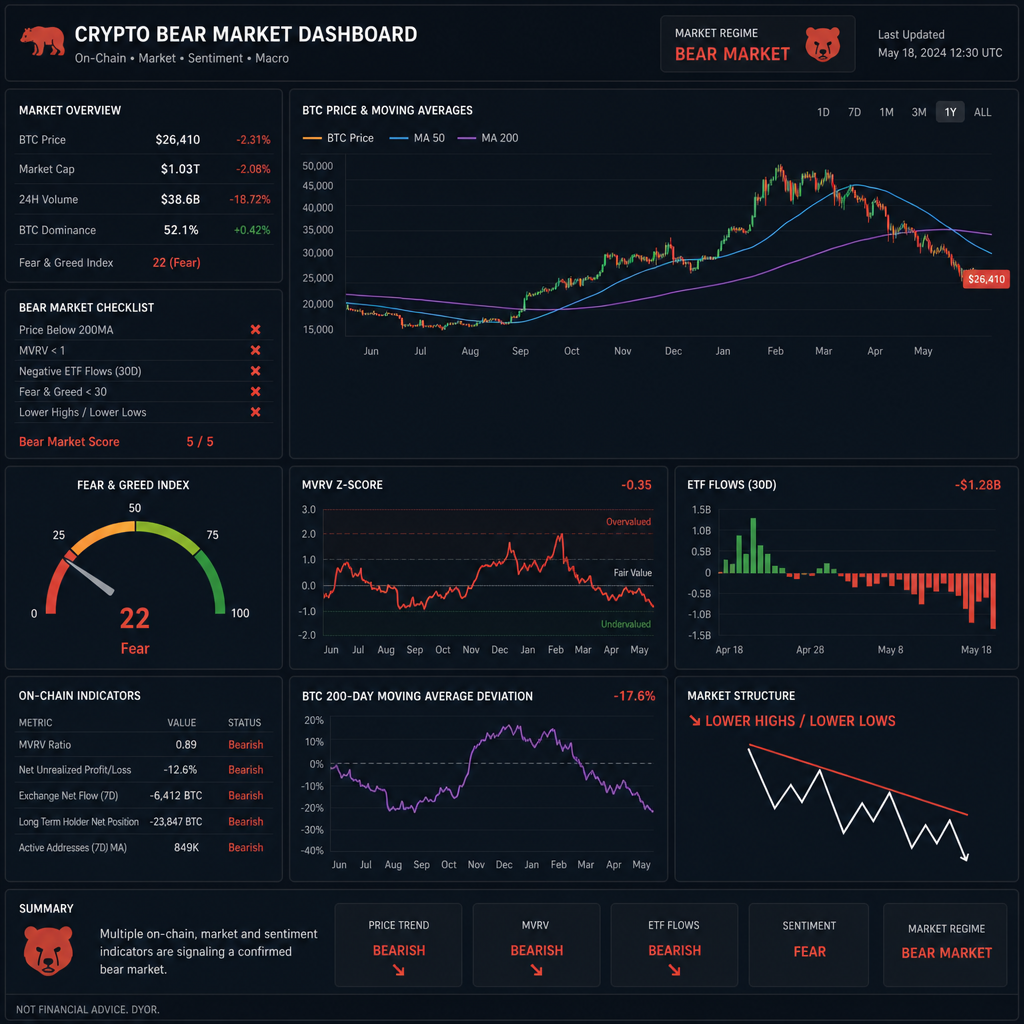
- The Crypto Fear & Greed Index reads 57, “Greed,” down from 69 the previous day. That is not the emotional capitulation usually associated with a mature bear-market bottom.
- Bitcoin dominance is 58.72% . High dominance can reflect capital concentrating in Bitcoin while altcoins weaken, but dominance alone is not a complete market-breadth measure.
Data timestamps differ by source. Bitcoin, MVRV, realized-price and dominance figures were checked on October 13; ETF data run through October 12; stablecoin supply is the latest DefiLlama reading; the Fed target range comes from the September 16 decision.
What counts as a crypto bear market?
A fixed 20% decline is a common stock-market convention, but it is too blunt for crypto. Bitcoin can fall 20% during an active bull trend and recover quickly. A more useful crypto definition combines four independent evidence groups:
- Price regime: a deep drawdown, weaker rebounds and persistent lower highs.
- Demand and liquidity: falling ETF demand, contracting stablecoin supply or weaker spot participation.
- Holder profitability: MVRV, realized price and recent-holder cost basis moving from profit into sustained loss.
- Participation and macro: deteriorating breadth, altcoin weakness, expensive leverage and restrictive monetary policy.
BlockchainReporter does not assign one point to every indicator or claim that “four red lights” prove a bear market. The indicators are not equally important, and several can measure the same underlying pressure.
For this tracker, a stronger bear-market confirmation would require:
- persistent price-regime weakness; and
- deterioration in at least two of the other three evidence groups; and
- confirmation over multiple weekly observations rather than one volatile session.
This is a transparent editorial rule, not a backtested model.
Has the 2026 crypto bear market already started?
There are two defensible answers because “start” depends on the definition.
Price-only answer: yes
Bitcoin is more than 20% below its October 6, 2025 record and has not reclaimed that high for 371 days. Under the traditional threshold, the bear market has already begun.
Regime answer: transition, not full capitulation
The drawdown and ETF reversal support a bear case, but several conditions remain less severe than at historical Bitcoin bottoms:
- MVRV is above 1, so aggregate holders remain in unrealized profit.
- Bitcoin trades above the short-term-holder realized price, so the average recent buyer is not yet underwater.
- Stablecoin supply is slightly higher over 30 days, which does not show broad liquidity withdrawal.
- Sentiment is still classified as Greed rather than persistent extreme fear.
The more precise conclusion is that the market is already structurally damaged, but the available data do not confirm a final capitulation regime .
What previous Bitcoin bear markets show — and what they do not
Bitcoin’s completed bear markets have been much deeper than a 20% decline.
| Cycle | Peak-to-trough drawdown | Approximate duration |
|---|---|---|
| 2013–2015 | −87% | About 400 days |
| 2017–2018 | −84% | About 350 days |
| 2021–2022 | −77% | About 380 days |
| Current drawdown from Oct. 2025 ATH | About −34.1% | 371 days since the high; final trough unknown |
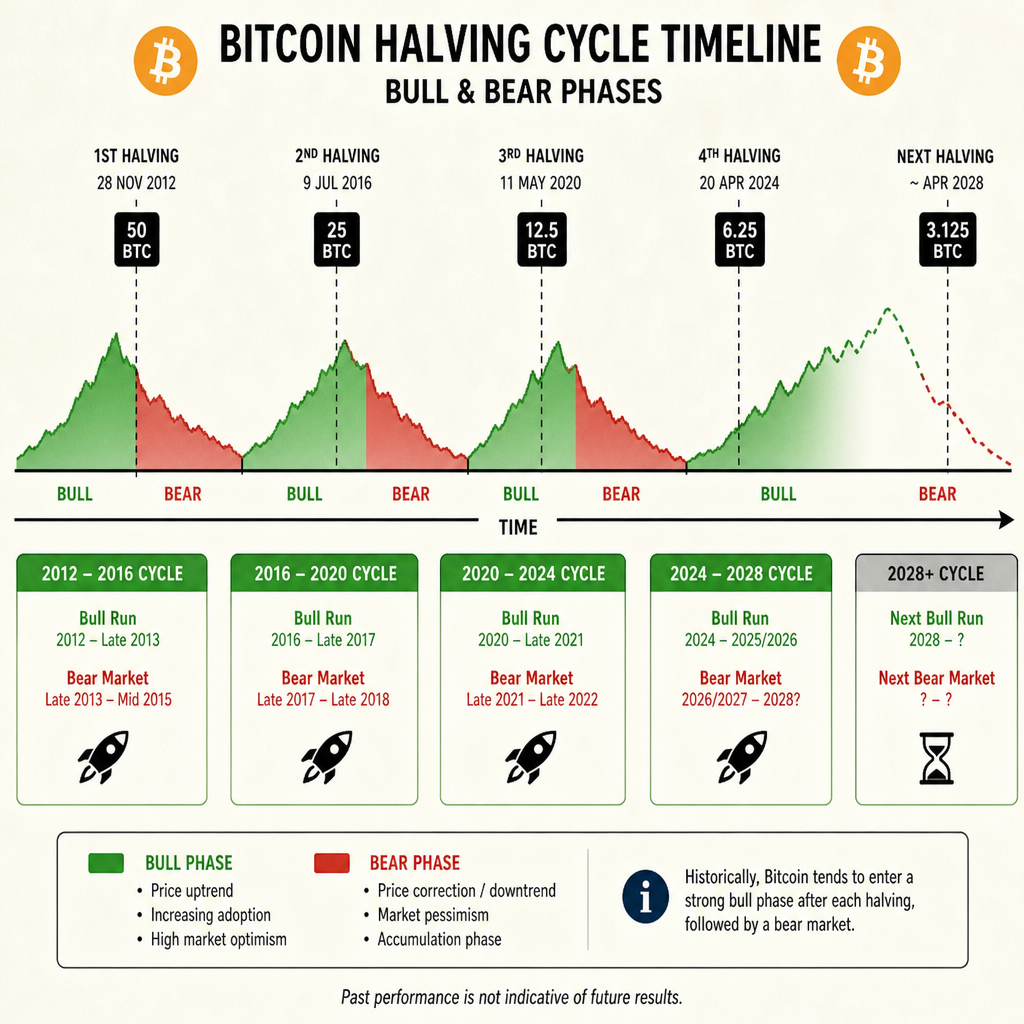
The historical record does not mean Bitcoin must fall 77% again. The asset, market access and institutional ownership have changed. It also does not prove that a bottom must arrive after roughly one year.
History is useful for defining possible severity and duration. It is not a calendar.
Indicator 1: Bitcoin’s drawdown and recovery structure
Bitcoin trades around $83,261 versus a Bitbo all-time high of $126,277.05, a drawdown of approximately 34.1%.
That is large enough to qualify as a bear market under a conventional price definition. The stronger regime question is whether recoveries can rebuild the prior structure.
A bearish pattern would include:
- rebounds that fail below previous highs;
- weaker participation on each recovery;
- repeated losses of important holder cost bases;
- downside expansion after positive news.
A single daily candle cannot establish this. The signal becomes more useful when the same behavior persists over weekly and monthly periods.
BlockchainReporter’s live Bitcoin price hub tracks the current market level. This article uses the drawdown as one part of a broader market-regime classification rather than treating price alone as the answer.
Indicator 2: MVRV and aggregate holder profitability
MVRV compares Bitcoin’s market value with realized value, which estimates the aggregate price at which coins last moved on-chain.
Bitbo shows:
- realized price: about $53,902 ;
- MVRV: 1.54 .
An MVRV of 1.54 means market value is approximately 54% above realized value. Aggregate holders therefore still carry unrealized profit.
Historically, MVRV below 1 has appeared near severe bear-market zones, when the average coin is valued below its last-moved price. But it is not a precise bottom timer. A market can stay weak for months before or after crossing that level.
Current reading: bearish conditions have reduced profitability from cycle highs, but aggregate capitulation is not confirmed.
Indicator 3: short-term-holder cost basis
The short-term-holder realized price estimates the average on-chain cost basis of coins that moved within roughly the last 155 days.
Bitbo lists the current level near $74,509.50 . At approximately $83,261, Bitcoin is about 11.7% above that cost basis.
Why it matters:
- above the level, the average recent holder remains in profit;
- below it, newer buyers are under pressure and may become more price-sensitive;
- a brief break is less meaningful than several weekly closes below it.
This is one of the clearest pieces of counterevidence to an already mature bear-capitulation thesis. The cushion is not large, but it still exists.
Indicator 4: spot Bitcoin ETF demand
U.S. spot Bitcoin ETF flows turned negative in October after a strong September.
Farside Investors reports:
- Oct. 1: +$102.7M
- Oct. 2: +$189.9M
- Oct. 5: −$89.8M
- Oct. 6: +$118.8M
- Oct. 7: −$484.9M
- Oct. 8: −$244.1M
- Oct. 9: +$21.1M
- Oct. 12: −$65.4M
The total from October 1 through October 12 is approximately −$451.7 million .
That reversal matters because regulated funds are now a material demand channel. However, one negative month-to-date reading does not prove a long-term distribution regime. ETF flows can be volatile, and they represent one segment of Bitcoin demand.
For related context, see BlockchainReporter’s analysis of Bitcoin holding above $84,000 despite heavy ETF outflows and its breakdown of why Bitcoin fell below $83,000 .
Current reading: a clear bear warning, but not independent confirmation.
Indicator 5: market breadth and Bitcoin dominance
A healthy crypto recovery normally spreads beyond one large asset. A weak market can look stable at the Bitcoin level while smaller tokens continue to lose liquidity and relative strength.
Bitbo shows Bitcoin dominance near 58.72% . High dominance may indicate capital concentrating in Bitcoin rather than moving broadly into riskier cryptoassets.
But dominance has limits:
- it can rise because Bitcoin is strong;
- it can rise because altcoins are weak;
- stablecoin-market-cap changes can affect the denominator;
- it does not show how many assets are above trend or generating real activity.
A better breadth dashboard would track a consistent universe of liquid assets and measure participation over time. Until BlockchainReporter maintains that dataset, dominance should be treated as a proxy , not a complete breadth signal.
Current reading: consistent with altcoin stress, but low-confidence as a standalone regime indicator.
Indicator 6: stablecoin liquidity
Stablecoins are not identical to fresh investment capital, but their aggregate supply is a useful proxy for dollar-linked liquidity available inside crypto markets.
DefiLlama reports:
- total stablecoin market cap: approximately $305.933 billion ;
- seven-day change: −0.54% ;
- 30-day change: +0.72% .
The weekly contraction is a caution. The positive 30-day reading is counterevidence to a broad liquidity collapse.
A stronger bear confirmation would be a persistent decline in total stablecoin supply, especially if it coincides with ETF outflows, falling spot volume and weaker on-chain activity.
Current reading: mixed. Liquidity has softened recently but has not contracted over the full 30-day window.
Indicator 7: Federal Reserve policy and macro liquidity
The Federal Reserve raised its target range by 0.25 percentage point to 3.75%–4.00% on September 16, 2026 and said inflation remained elevated.
Higher policy rates can pressure crypto through several channels:
- cash and short-duration government debt become more competitive;
- leverage becomes more expensive;
- portfolio managers may reduce high-volatility exposure;
- tighter financial conditions can weaken liquidity.
The next scheduled FOMC meeting is October 27–28, 2026 .
A future policy shift toward easier conditions could weaken the bear case. Further tightening or delayed easing would strengthen the macro headwind. Monetary policy does not determine Bitcoin by itself, but it changes the environment in which demand and leverage operate.
Current reading: restrictive macro backdrop.
Sentiment cross-check: greed is not capitulation
Alternative.me’s Crypto Fear & Greed Index reads 57, “Greed,” compared with 69 the previous day.
The drop shows sentiment cooling, but 57 is far from sustained extreme fear. A mature bear-market bottom has usually felt worse than a moderate Greed reading.
The index should not be used as a buy or sell signal. It combines volatility, momentum, social activity, dominance and search trends, which can overlap with other indicators in this framework.
Current reading: market confidence has weakened, but emotional capitulation is not visible.
Three scenarios for the rest of 2026
Scenario 1: confirmed bear-market regime
This becomes more credible if:
- Bitcoin loses the short-term-holder realized price for several weeks;
- MVRV trends toward 1;
- ETF outflows persist through attempted rallies;
- stablecoin supply contracts over 30 days;
- altcoin breadth deteriorates further;
- the Fed maintains or increases restrictive policy.
This scenario does not require a one-day crash. A slow sequence of failed recoveries can confirm it.
Scenario 2: transition and wide range
This is the current BlockchainReporter base classification.
Conditions:
- Bitcoin remains far below its record but above key holder cost bases;
- ETF flows alternate between inflows and outflows;
- stablecoin liquidity stays broadly flat;
- MVRV remains above 1;
- macro policy stays restrictive without a new shock.
The market can produce large rallies inside this regime without resolving the larger question.
Scenario 3: recovery / cycle extension
This becomes more credible if:
- ETF demand turns persistently positive;
- Bitcoin reclaims a sequence of prior highs;
- participation broadens beyond Bitcoin;
- stablecoin supply expands;
- recent holders build a larger profit cushion;
- policy expectations become less restrictive.
A recovery does not require every indicator to become bullish at once, but price, demand and liquidity should stop contradicting one another.
What would invalidate the current classification?
The current “transition / bear warning” label should be changed if the evidence changes.
Upgrade to confirmed bear regime if persistent price weakness is joined by clear holder losses and contracting liquidity.
Downgrade to recovery regime if Bitcoin rebuilds trend structure while ETF and stablecoin demand improve and market participation broadens.
Do not preserve a label to defend an old article. This page should be updated from the same canonical URL when the underlying readings materially change.
A practical risk plan
No indicator can tell an individual investor what to do. A better use of the framework is to define actions before volatility forces a decision.
- Define the regime trigger. Decide which combination of price, flows and holder profitability would change your risk level.
- Remove leverage first. A leveraged position can be forced out before a long-term thesis has time to recover.
- Separate Bitcoin from weak-token risk. Bitcoin’s recovery history does not transfer automatically to every altcoin.
- Keep liquid reserves. Cash and stablecoins have different risks; stablecoins add issuer, custody and peg exposure.
- Review monthly, not hourly. A regime develops through persistent conditions, not one headline.
- Record the source and date. A dashboard is useful only when the reader knows when each value was checked.
Methodology and update policy
BlockchainReporter groups the evidence into four pillars:
- price regime;
- demand and liquidity;
- holder profitability;
- participation and macro.
The classification is editorial and is not statistically backtested. Indicators are not equally weighted. A duplicate metric cannot create additional confirmation simply because it appears in two charts.
Update this page when at least one of the following occurs:
- Bitcoin changes by more than 10% from the previous snapshot;
- MVRV or the short-term-holder cost basis changes regime;
- monthly ETF flows change sign;
- stablecoin supply changes direction over 30 days;
- the Federal Reserve changes its target range;
- a new cycle high or low materially changes the drawdown.
The data in this version were checked on October 13, 2026. Market values must be refreshed before publication if more than 24 hours have passed.
Frequently Asked Questions
Under the conventional 20% drawdown definition, yes: Bitcoin is about 34% below its record. Under a broader crypto-regime definition, BlockchainReporter classifies the market as a transition / bear-warning regime because ETF demand has weakened but aggregate and recent holders remain in profit and stablecoin liquidity has not contracted over 30 days.
Not by itself. Crypto regularly experiences 20% corrections. Duration, failed recoveries, liquidity, holder profitability and participation matter more than one fixed percentage.
The completed 2013–15, 2017–18 and 2021–22 Bitcoin bear markets lasted roughly 350–400 days from peak to trough in the cited cycle data. That history does not guarantee the duration of the current cycle.
No single indicator is sufficient. Price structure is essential, while MVRV, recent-holder cost basis, ETF flows, stablecoin liquidity, market breadth and macro policy help confirm or challenge the price signal.
Persistent ETF inflows can absorb supply and support demand. Persistent outflows can remove that support. ETFs are now an important channel, but they do not represent the entire global Bitcoin market.
It cannot be known in real time. Bitcoin remains well above realized price and the short-term-holder cost basis, so the data do not resemble full aggregate capitulation. A later low, a higher low or no deeper low are all still possible.
BlockchainReporter Analysis
The current evidence does not support a clean “bull” or “bear” label without qualification. Bitcoin’s 34% drawdown and October ETF outflows are genuine warnings. MVRV above 1, recent holders still in profit and positive 30-day stablecoin growth are meaningful counterevidence.
The practical conclusion is not to predict November, December or a single crash date. It is to monitor whether weakness spreads from price into holder losses, institutional demand and crypto liquidity. When those independent evidence groups deteriorate together, the bear-market case becomes much stronger.
This article is educational and does not provide personalized investment advice.
Sources
- Bitbo live Bitcoin metrics — price context, all-time high, drawdown, realized price, MVRV, short-term-holder realized price and Bitcoin dominance.
- Farside Investors Bitcoin ETF flows — daily U.S. spot Bitcoin ETF net flows.
- Alternative.me Crypto Fear & Greed Index — sentiment reading and methodology.
- DefiLlama stablecoin dashboard — total stablecoin supply and recent change.
- Federal Reserve September 16, 2026 statement — federal funds target range.
- Federal Reserve FOMC calendar — next meeting date.
- BIT Knowledge Hub: Bitcoin bear markets — historical drawdowns and durations.
- BIT Knowledge Hub: MVRV explained — MVRV methodology and limitations.
- Glassnode short-term-holder realized price chart — definition and source series.